Korea's Year-End Tax Settlement: Key Adjustments to Make Before December 31
Year-end tax settlement refunds are determined not in January, but by December 31 of the previous year. Anchored on the structural difference between income deductions and tax credits, this article filters which items can still be adjusted and which are already locked.
Table of Contents
As the December calendar turns to its final page, advertisements from financial institutions pour in all at once, claiming that opening an account right now will get you tax money back in your year-end settlement. Yet many salaried workers simply open the Hometax screen the following January and enter numbers as prompted, never understanding which items cut taxes and why. The refund amount is actually finalized not in January, but on December 31 of the preceding year. You need to distinguish which levers remain actionable and which are already permanently closed.
Refunds Exist Because the National Tax Service Pre-Collects Taxes
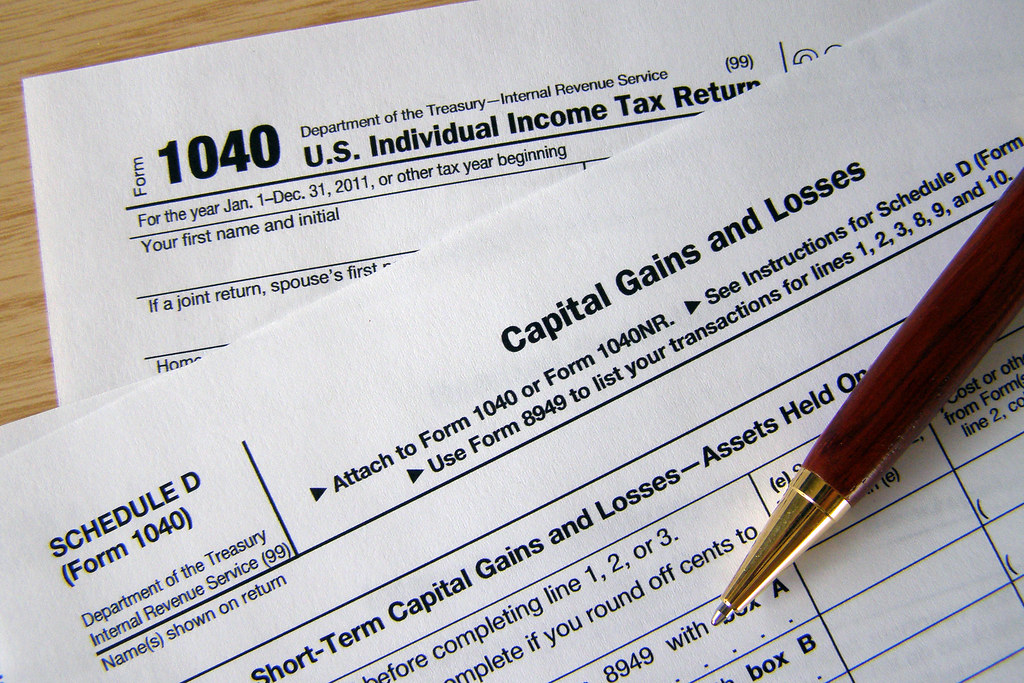 Photo: ccPixs.com / flickr (CC BY)
The reason money returns to you in year-end tax settlement is that the National Tax Service withholds annual taxes in advance based on rough approximations. The 42-minute video titled "Year-End Tax Settlement: Let's Reduce Taxes" (https://www.youtube.com/watch?v=gROGVJthxM8) on the YouTube channel Syuka World places this mechanism front and center. Income tax is withheld from an employee's paycheck before it hits their bank account using a standardized provisional benchmark called the simplified tax withholding table. Because an identical table is applied to every employee, it inevitably diverges from each individual's actual deductions and expenditures; reconciling this gap at year's end is the year-end settlement process. The host explains that tax authorities withhold upfront because collecting after the fact is exceedingly difficult once funds have already been spent. If the final screen displays a negative number, you receive a refund; if it displays a positive number, you must pay the unpaid balance.
There is a prerequisite to keep in mind: this video was published ahead of the 2025 year-end, and the host noted early on that specific provisions might have changed for that tax year. Year-end tax rules undergo annual adjustments to caps and deduction percentages, so numerical figures must be evaluated within that specific timeframe. There is no guarantee current rules remain identical. Even so, the core architecture remains invariant: understanding where deductions apply in the formula and why they are placed there changes very little over time. Grasping this underlying architecture provides far greater long-term value than memorizing individual statutory ceilings.
While the video runs 42 minutes, its core formula is straightforward. Tax is modeled as taxable income multiplied by a tax rate. Deductions split into those that reduce income before applying the tax rate and those that reduce calculated tax directly, with specific items populated across each bucket. The income deduction bucket includes personal exemptions, social insurance premiums, housing funds, and credit card expenditures. The tax credit bucket includes child credits, medical expenses, education expenses, monthly rent, donations, small-business employment relief, and pension accounts. The host highlights credit card spending and pension accounts as the two items directly controllable by the individual, calling the pension account tax credit "the crown jewel of tax credits."
Income Deductions vs. Tax Credits: Different Placement Favors Different Taxpayers
 Photo: Michal Kulesza / stocksnap (CC0)
Even within the same broad deduction category, the stage at which an item is deducted changes who benefits most. An income deduction reduces taxable income prior to multiplying by the tax bracket rate; therefore, the actual tax savings equal the deducted sum multiplied by the taxpayer's marginal rate. This means that higher earners derive significantly greater financial value from an identical 1-million-won income deduction. In contrast, a tax credit subtracts a predetermined sum directly from the final calculated tax bill, delivering an identical nominal benefit regardless of marginal tax brackets. The video's observation that income deductions grow more vital as earnings rise stems directly from this arithmetic.
This fundamental rule clarifies numerous real-world strategies. For dual-income couples deciding which spouse should claim dependent exemptions, the answer follows this exact principle. Personal exemptions are income deductions subtracting 1.5 million won per dependent from taxable income; consolidating them under the spouse in the higher tax bracket maximizes the net tax reduction. Conversely, for tax credit items, switching claimant names leaves the total tax reduction largely unchanged. Checking whether an item reduces income or directly offsets tax establishes an immediate decision-making framework, even when encountering an unfamiliar deduction for the first time.
Furthermore, contribution limits, deduction rates, and actual refund amounts represent three distinct metrics. The video repeatedly warns against conflating them. For example, guaranteed insurance carries a 1-million-won ceiling at a 12% credit rate; medical expenses exceeding 3% of gross salary carry a 7-million-won cap at a 15% rate; monthly rent for non-homeowning household heads earning 80 million won or less is capped at 10 million won at a 15% rate. A 7-million-won medical cap does not mean taxes drop by 7 million won; only the eligible amount multiplied by the deduction rate is refunded. Most dashed expectations arise from skipping this multiplication step.
Weak Points - Money Spent Solely to Save Taxes Is Almost Always a Net Loss
 Photo: Green Chameleon / stocksnap (CC0)
The primary blind spot in this video is presenting the credit card income deduction as a centerpiece without explicitly warning that spending more money simply to earn deductions is a losing financial proposition. As explained in the video, credit card deductions apply only to expenditures exceeding 25% of gross salary, with deduction ceilings capped at 3 million won for salaries under 70 million won (and 2.5 million won above that). Furthermore, the credit card deduction rate is only 15%. Tracing these numbers leads to an inescapable conclusion: spending an additional 1 million won yields a 150,000 won income deduction, which reduces actual taxes by only that amount multiplied by your tax rate. Cash outflow vastly exceeds cash refunded. A credit card deduction is merely a secondary rebate on money you were already going to spend based on payment method optimization; it is never a rational justification to increase consumption.
This omission is particularly glaring because the video successfully identifies the exact same fallacy in another category. In discussing charitable donations, the host points out that donating 30 million won on a 100-million-won salary yields only around 7.5 million won in tax credits, flatly emphasizing that donating to save on taxes puts the cart before the horse. That logic is entirely sound. Yet the video fails to apply that exact same scrutiny to credit card spending. Donations involve visible lump sums making losses obvious, whereas card swipes are fragmented into smaller transactions; structurally, however, both mechanics are identical.
The treatment of pension accounts similarly lacks balanced perspective. The video calculates that a 6-million-won pension savings contribution with a 13.2% or 16.5% credit rate yields 990,000 won for gross salaries under 55 million won (or 792,000 won above that threshold), expanding to 1.485 million won or 1.188 million won when paired with an IRP up to 9 million won. Tax deferral, low pension taxation, and netting of gains and losses are methodically highlighted. While informative, the account's primary constraint—funds remaining locked until age 55—is not treated as an economic cost. Penalties for premature liquidation are mentioned only fleetingly during a sponsored platform walkthrough toward the end. For savers with planned lump-sum needs such as housing or tuition, maxing out these accounts may be sub-optimal, yet this critical trade-off is overlooked.
The overall presentation structure also invites scrutiny: from minute 36:29 through the end of the 42-minute video, content consists of a brokerage product sponsorship. Because elevating pension accounts to the pinnacle of tax strategy transitions seamlessly into marketing specific brokerage offerings, the boundary between objective education and advertising blurs. Even with sponsorship disclosures in place, viewers cannot easily determine whether the preceding 35 minutes of guidance were designed to channel them toward the sponsor's product.
Dual-Income Deduction Allocation Diverges in Opposite Directions by Category
 Photo: Author Unknown / rawpixel (CC0)
The most practical topic for dual-income couples is deduction consolidation, yet the video addresses it along a single dimension: the rule of thumb to funnel deductions to the higher earner. Because personal exemptions are income deductions, allocating them to the spouse in the higher tax bracket yields greater tax savings, and the video argues that optimizing credit card caps likewise favors the higher earner first. The sole exception provided is when combined spending is low: if neither spouse can surpass their individual 25% threshold, pooling spending onto the lower earner makes sense because their lower salary sets a lower hurdle to cross.
However, carrying this logic forward yields an additional conclusion the video completely omits. Medical expense tax credits apply only to expenditures exceeding 3% of gross salary. Because this threshold scales with salary, its structure mirrors the 25% credit card hurdle. Therefore, medical expenses are far easier to qualify for when consolidated under the spouse with the lower income. Furthermore, because medical expenses are a direct tax credit, shifting them to the higher-earning spouse produces zero additional tax savings. Blindly applying the single rule of funneling everything to the higher earner across all categories results in financial losses. You must evaluate whether an item features a qualifying threshold, and whether it operates as an income deduction or a tax credit.
In summary, three distinct rules govern these choices: threshold-free income deductions belong with the higher earner; deductions with thresholds proportional to income belong with whichever spouse can clear the hurdle; and flat tax credits should prioritize qualification rather than earner rank. In practice, optimal choices depend on each spouse's specific salary and expenditure mix, so mastering these structural rules and plugging in your personal numbers provides the safest path. The video's analytical framework for credit cards is accurate; it simply failed to apply that framework across the remaining categories.
Overall Assessment: Agreement on Diagnosis, Conditional Agreement on Prescription
Agreement rests on the structural breakdown of the tax system. Demystifying how the National Tax Service withholds provisional taxes using simplified tables and reconciles balances as of December 31 provides clarity for taxpayers who previously entered data into Hometax without understanding the mechanics. Highlighting that income deductions and tax credits operate at different stages of the formula to benefit different income profiles aligns with tax realities. The distinction between income deductions scaling with marginal tax rates and tax credits delivering uniform reductions across brackets remains durable regardless of regulatory updates or changing caps.
Reservations center on the prescriptive advice. Presenting credit card deductions as a headline strategy without warning that spending money for deductions creates a net financial loss creates a significant blind spot. Explicitly warning against donating for tax benefits while failing to apply that same logic to credit card spending highlights this imbalance. The recommendation for dual-income couples is similarly incomplete: relying solely on the rule of funneling everything to the higher earner can backfire on items like medical expenses that feature salary-proportional thresholds.
3 Action Items for Today
- Check whether your credit card spending has crossed the 25% gross salary threshold.
- Fill eligible pension savings and IRP contribution limits before December 31.
- Collect frequently overlooked receipts, including postpartum care centers, LASIK surgery, and educational expenses.
A year-end tax settlement refund is not newly generated income; it is simply the return of your own overpaid money. Checking whether an item reduces income or tax directly and whether it carries a qualification threshold clarifies almost every decision. Grasping this structural framework proves far more useful over time than trying to memorize statutory figures that change with every tax year.